Bank Heist
Smaller banks have one big advantage to steal customers from the big guys.
42% of respondents switched banks or considered it in the past three years, and 9% made the jump, according to a 401-person study by PETERMAYER’s Brand Joy Lab. The people most likely to switch feel behind financially but believe a great bank could change their trajectory, which gives community banks with a real story an edge.
- Published
- Updated
Key findings
42% of respondents switched banks or seriously considered switching in the past three years, according to PETERMAYER’s Brand Joy Lab (n = 401; fielded Apr 2026).
9% of respondents switched completely to a new primary bank in the past three years, according to PETERMAYER’s Brand Joy Lab (n = 401; fielded Apr 2026).
53.3% of respondents who switched or considered switching (n = 167) often feel behind financially, against 40.2% of those who haven't considered it (n = 234), according to PETERMAYER’s Brand Joy Lab (n = 401; fielded Apr 2026).
55% of near-switchers (n = 78) trust their bank to be upfront about fees, against 79% of loyal customers (n = 234), according to PETERMAYER’s Brand Joy Lab (n = 401; fielded Apr 2026).
Why do people switch banks?
Thousands of whitepapers have answered this question. Once or twice, our agency has answered it for our financial services partners.
And every time we get an answer—features, rates, incentives, tech, personalization—every player in the category races to copy what’s working. We end up in the same place we started.
Every. Bank. Looks. The. Same.
I think we’re asking the wrong question. We should be asking who switches banks.
There’s not a lot of great data on this topic, so we ran a 400-person study through the Brand Joy Lab to understand the consumer at the center of this problem.
Almost half of the respondents told us they had, or had considered, switching banks in the last three years (only 9 percent made the jump, which falls in line with industry research).
We went beyond demographics to understand the emotional stakes of switching. The findings tell a story of Americans who are falling short of their own expectations but have hope that a great bank—yes, a bank!—could change things.
- 401 consumers surveyed
- 42% switched or considered it
- 9% actually made the jump
Who switches banks, and what do they need to feel to make the jump?
People hire banks to free them from fear, not handle transactions.
How much joy each banking moment brings

Show the data
| Banking moment | Score (0–100) |
|---|---|
| Knowing my money is safe and protected | 81.6 |
| Feeling welcomed and respected, not evaluated or judged (regional / community-bank customers) | 81.5 |
| Knowing exactly what I will and will not be charged | 78.9 |
| Knowing you can afford the things you need (Joy Index) | 76.9 |
| Visiting a bank branch (Joy Index) | 25.1 |
| Borrowing money from a bank (Joy Index) | 4.4 |
When people describe the joy their bank brings them, peace comes up most. Security. The feeling that someone has their back. Ask those same people about taking out a loan and the emotional register flips entirely. The distance between those two experiences, between banking as shelter and banking as transaction, tells you everything about the job people actually want done.
A Millennial earning under $25,000 a year described what a good banking relationship felt like:
Encourage and remind me every day of the tools to use. Remind me to keep saving because it’s worth it.
The switcher is an optimist, but they feel unfulfilled
Feeling behind, and feeling things can change

Show the data
| Statement | Switching / considering switching | Happy with my bank |
|---|---|---|
| I often feel behind financially. | 53.3% | 40.2% |
| A great banking relationship could change my trajectory. | 55.1% | 54.3% |
The customers most likely to switch banks aren’t just shopping for a better rate. More than half feel behind where they expected to be at this stage of life, and they still believe, at nearly the same rate, that the right banking relationship could change their trajectory. That combination of pressure and belief moves people.
A Gen X man in the survey described what he wanted from his bank in three words: “To understand me.”
The customer who considered switching and stayed put registers lower on both optimism and satisfaction. Not desperate enough to act, not convinced enough to go looking. They’re parked in a relationship, waiting for something to change.
People want to switch for more humanity and transparency. But it’s the experience that pushes them.
How my current bank delivers against my needs

Show the data
| Statement | Near-switchers | Loyal customers |
|---|---|---|
| I trust my bank to be upfront about fees. | 55% | 79% |
| My bank treats me as an individual. | 44% | 71% |
The customer most worth reaching already wants what a community bank offers. Near-switchers rate low fees and the ability to speak to a real person as their top two priorities in a banking relationship.
A Millennial woman from the Midwest described what she wanted: “More personalized guidance, clearer tools to improve my finances, and greater transparency on how I can grow financially with them.”
She hasn’t switched yet. Nearly one in three actual switchers cite a frustrating or disappointing experience as the final trigger. That moment arrives eventually. The regional bank that has already made itself visible gives that customer somewhere to land when it does.
Banking differentiation was always about the community. Features come second.
These banks don’t treat community involvement as a line on their website. They invest deeply in telling and promoting the stories of their people and the ways of life of the communities they serve.
Frost Bank | Texas
Telling customer stories
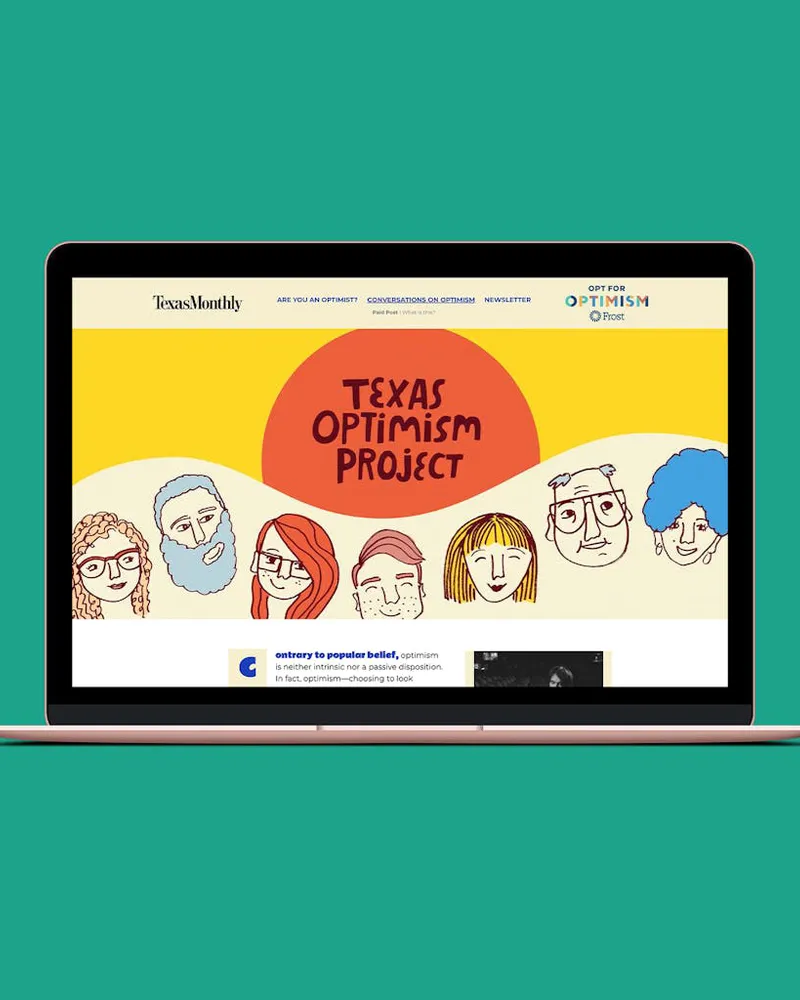
Frost Bank operates across Texas with the scale of a regional institution and the instincts of a neighborhood one. To go beyond advertising products, Frost partnered with Texas Monthly to produce the Texas Optimism Project, which includes 60 pieces of content and 35 podcast episodes built entirely around the lives of Texans.
More recently, they’ve run campaigns anchored to real stories of service from their own employees. The message has stayed consistent for years: people come first. When your advertising and your behavior are speaking in tandem, customers notice.
Legends Bank | Tennessee
Being there on the community’s worst days
An internal volunteer program that shows up when it matters most.
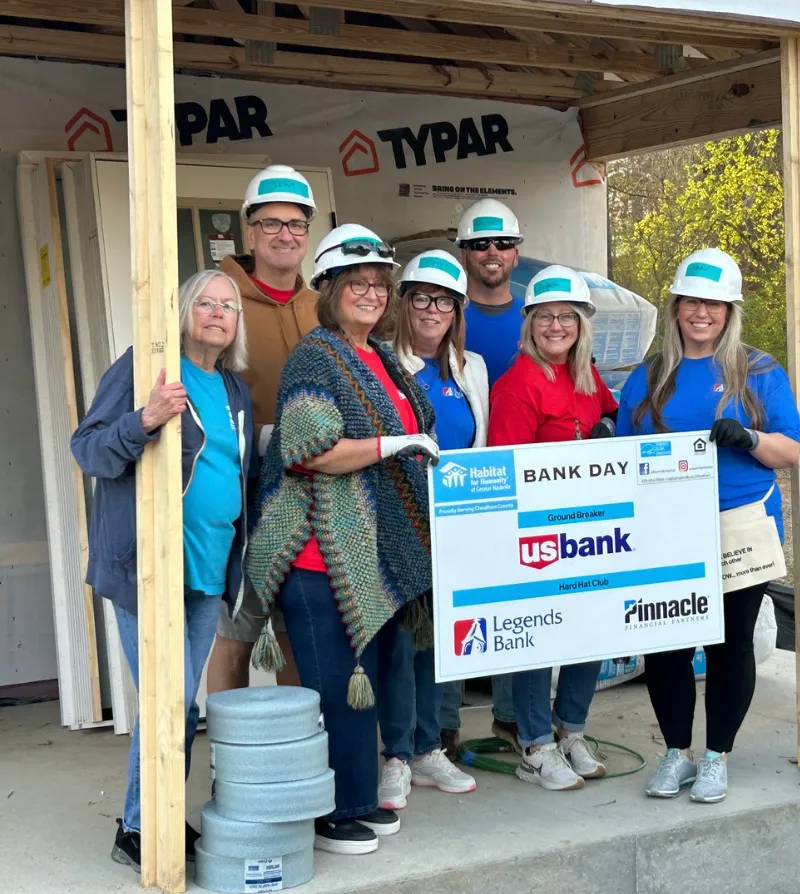
Legends Bank, a community bank in Clarksville, Tennessee, built an internal volunteer program called Legends Lift to mobilize employees during natural disasters and community crises. When tornadoes and floods hit Middle Tennessee, bank staff deployed alongside military veterans and their families to run supply and relief operations that now reach roughly 40,000 families a month.
The infrastructure Legends Bank built to show up for its community, with a name, a structure, and a deployment model, says more about their brand than any advertising could.
Your community is your superpower. Your features are your credibility.
The banks doing this well aren’t outspending anyone. They’re just clearer about what they are, and consistent enough to prove it. For a regional or community bank with an honest story to tell, your point of difference lies in your people—both customers and associates.
How this report was built
This report draws on PETERMAYER’s Brand Joy Lab, a monthly omnibus panel of consumers in the United States. Its core findings are based on n = 401, fielded 2023–2026.
The full panel covers 15,346 respondents, August 2023 – October 2026. Joy is measured on a -3 to +5 scale and reported as the Joy Index (-60 to 100; 0 is neutral). Read the full Brand Joy Lab methodology.